The Default Is Still a Decision: A Calm Walk Through This Year's Open Enrollment

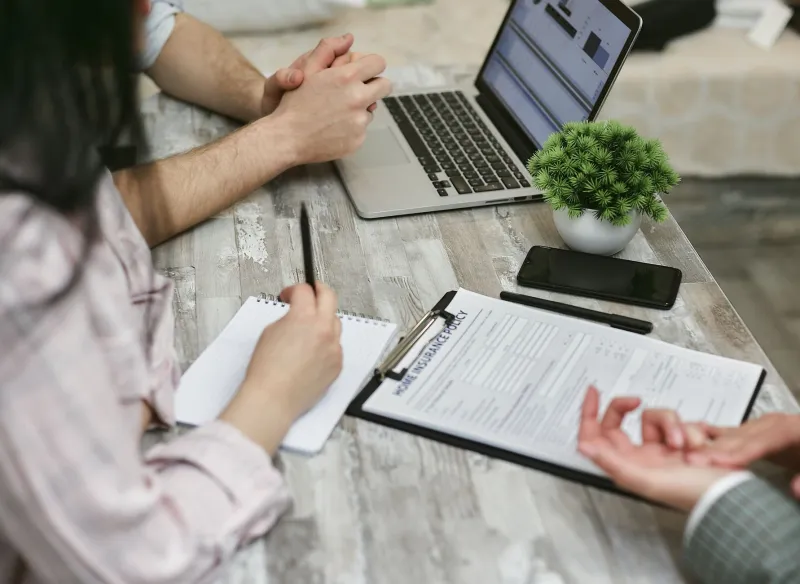
Photo by Photo by Vitaly Gariev on Unsplash on Unsplash
The Default Is Still a Decision
Every November the emails start arriving. Your open enrollment window is now open. Then a reminder. Then another one, this time with a subject line in all caps. And every year a lot of us do the same thing: open the portal, click through the screens, accept whatever was already selected, and get back to our lives.
That's understandable. Benefits paperwork is dense, the plan names sound like airport codes, and the whole thing feels like it should come with a translator. But here's the quiet catch — skipping the review isn't neutral. Your employer probably renegotiated the plans, your premium share may have shifted, and a prescription you take every month may have moved to a different tier. Doing nothing is still a decision. It's just a decision you didn't get to see.
The good news is that you don't need to become a benefits expert. You need about forty-five minutes, a recent pay stub, and one rule: make at most one or two small changes, and only where you actually understand the trade-off. That's it. This is a check-up, not a makeover.
Start with the paper you already have
Before you open the enrollment portal, pull up your most recent pay stub. Find the line where your health premium comes out. Write that number down — the per-paycheck amount, not the annual total.
That single figure is your anchor. It's what you're currently paying, in real money, every two weeks or twice a month. When you start comparing plans, you'll be comparing against something concrete instead of against a vague memory of what things used to cost.
While you're there, note your employer's contribution too, if it's listed. Some employers show it as a separate line. Seeing both numbers side by side is oddly reassuring — it reminds you that the sticker price of a plan and the part you actually pay are two different things.
Three numbers carry most of the weight
You can read forty pages of plan documents or you can find these three figures and understand about eighty percent of what you need:
Your premium per paycheck. What comes out of your wages.
The deductible. What you pay before the plan starts sharing costs, for most services.
The out-of-pocket maximum. The worst-case ceiling for the year. This is the number that matters if something big happens.
A plan with a lower premium and a much higher deductible isn't automatically the cheaper choice — it's the cheaper choice if you don't use much care. If you have a standing appointment schedule or a medication you take daily, run a rough estimate of your typical year against both plans. You don't need precision. You need to notice when the gap between the two options is large enough to matter.
If your employer offers a Summary of Benefits and Coverage document, that's the shortcut. It's a standardized few-page summary designed to be compared side by side. Use it instead of the full plan booklet.
Five minutes on doctors and prescriptions
This is the step people skip and later regret, and it takes less time than brewing coffee.
Open the plan's provider directory and check that your primary care doctor is still in network for the coming plan year. Then check any specialist you see regularly. Directories are imperfect, so if something looks off, a quick call to the number on your insurance card settles it faster than another round of searching.
Next, look up each prescription you take and confirm it's still on the plan's drug list, and at what tier. Tiers shift. A medication that was a modest copay can move up a level and suddenly cost meaningfully more. If that happens, it's not a disaster — it's a question for your doctor or the plan's member services line about alternatives. Better to ask in November than to find out at the pharmacy counter in February.
The HSA and FSA question, in plain English
Both accounts let you pay for eligible medical costs with money that isn't taxed. They behave very differently, though, and the difference is the whole point.
A health savings account only comes with a qualifying high-deductible health plan. Money goes in tax-free, grows tax-free, and comes out tax-free for eligible expenses, and unused balances roll over year to year. It can even be invested once you build a cushion. If you're generally healthy and can afford to contribute, an HSA is one of the few genuinely patient-money tools in the tax code — a slow build that follows you, even into retirement.
A flexible spending account is more like a use-it-or-lose-it fund. Some employers offer a grace period or a small rollover, but that's plan-specific, so read the fine print before you fund one aggressively. The upside is that it's available even if you're not on a high-deductible plan. The trick is to estimate low and contribute what you're confident you'll actually spend. Overfunding an FSA is the one mistake in this whole process that's hard to undo.
If you expect steady, predictable costs — regular visits, ongoing prescriptions, a kid in braces — an FSA can be the better fit. If your spending is lumpy and unpredictable, the HSA's rollover feature is worth a lot.
The dependent care line nobody mentions
Most enrollment portals have a section for dependent care — childcare, after-school programs, summer camp, or care for an older relative who depends on you. Contributions come out before taxes, which can meaningfully reduce what that care really costs you.
The catch is that you have to know roughly what you'll spend. Pull up last year's childcare receipts. If the total is steady, this is one of the least dramatic, most reliable wins on the entire form. If your situation is changing — a kid starting kindergarten, a parent moving in — estimate conservatively and adjust next year.
Make one change, then stop
Here's where the safely change part comes in. Resist the urge to overhaul everything because you're finally looking at it. Big swings in benefits are hard to evaluate and easy to regret.
Pick one or two modest moves. Bump your HSA contribution by a small, fixed amount you won't miss. Confirm your beneficiaries are current. Check that the supplemental coverage you've been paying for is something you'd actually claim. If your employer offers a matching contribution somewhere, make sure you're capturing all of it — that's free money and it's the closest thing to a sure thing in personal finance.
Then double-check the deadline and put a reminder on your calendar for three days before it closes. Portals get busy in the final hours, and a locked-out login is a lousy way to end the process.
Leave a note for next year
Before you close the tab, write five lines somewhere you'll find them: which plan you chose, why, what you're paying per paycheck, and what you'd want to revisit. Next November, that note turns a confusing hour into a ten-minute confirmation.
That's the whole idea. You don't have to optimize your benefits. You don't have to beat the system. You just have to look, decide on purpose, and let your paycheck stay boring. Boring is the goal.